Home Loan – Make Your Homeownership Journey Easier
HOME LOAN BASICS
Understand the property requirement, financial commitment and lender evaluation before proceeding.
Understanding a Home Loan
A Home Loan is generally a secured financial product used to fund the purchase, construction, or certain other eligible residential property requirements.
Typically, the property that is being financed becomes a factor in the lender’s decision. Apart from checking the applicant’s income and ability to repay, bank or NBFC verification will include details about legal documents related to the property, ownership records, market value, and technical specifications of the land.
A home loan is a long-term financial commitment that usually involves big amounts and the borrower should ascertain their complete financial commitment before this loan.
Simply, the lowest EMI/lowest advertised interest rate cannot decide. Even repayment costs, loan tenure, processing charges, down payment, and prepayment terms can affect the overall borrowing decision.
Loans Telangana helps customers understand these factors before exploring available Home Loan options.
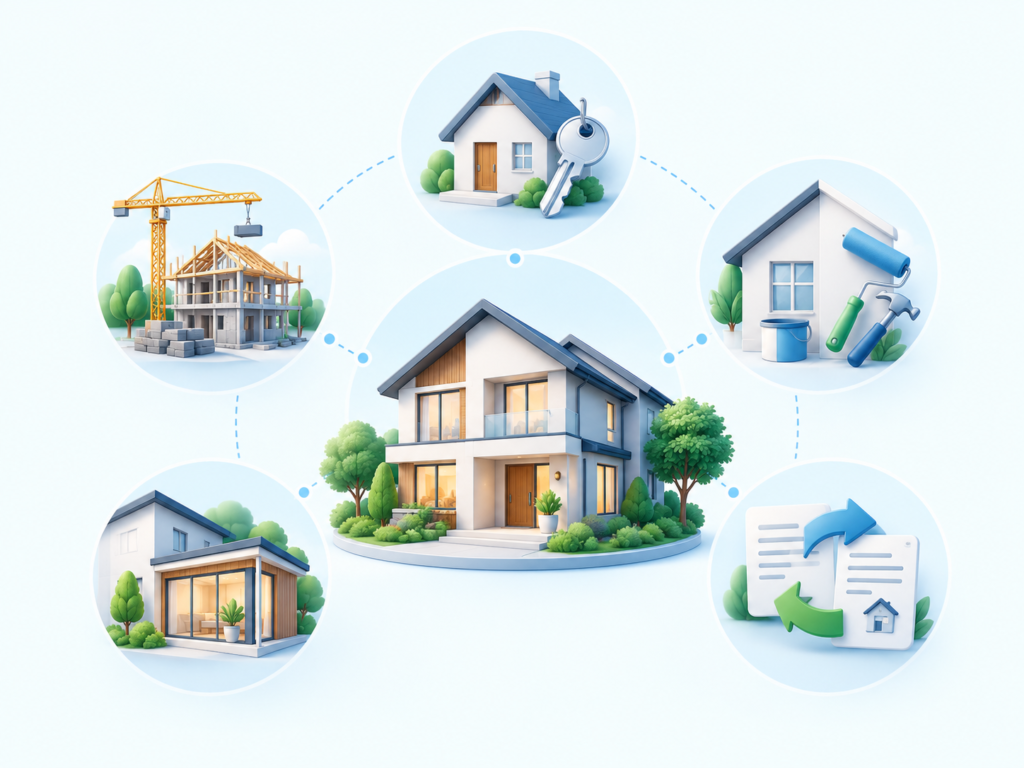
Types of Home Loans
Different customers have different housing requirements. Depending on the property requirements and lender policies, several types of Home Loan products may be available.
Home Purchase Loan
Most of the eligible customers apply for a Home purchase loan to fund their buying of flat, apartment or independent house. Before it finalises the eligible loan amount for an applicant, the lender usually assesses their income and repayment capacity as well as credit profile details along with property specifics.
Home Construction Loan
Customers who hold eligible land and want to build a property to reside in may look at applying for a Home Construction Loan. The lender can check land documents, sanctioned building plans, estimated construction cost and finances of the applicant before processing.
Home Improvement or Renovation Loan
It serves qualified homeowners with particular renovation, repair, or improvement needs. The expenses that qualify for loans to businesses and the amount of loan catered depends on various policies adopted by respective banks or NBFCs.
Home Extension Loan
A Home Extension Loan can be considered when an existing homeowner is looking at making additions to their living space (another room, another floor, or an eligible structural extension). Approved plans and property documents may be required.
Plot or Land Loan
Certain banks offer financial assistance for the purchase of approved residential plots for construction on those lands at a future date. Financing structure, Construction standards, and terms might be different from a normal Home loan.
Home Loan Balance Transfer
A Home Loan Balance Transfer may enable eligible borrowers to transfer a current Home Loan from one lender to another. But then, before going further, borrowers must weigh the new tenure at the new rate with transfer charges and potential savings in total.
Home Loan Top-Up
Existing Home Loan borrowers who meet the eligibility criteria may look at a Top-Up Loan for more funds. Over the amount of loans get, how much they will lend, what they are going to cost you and how repayments will be made is up to the lender.
Which Home Loan Option May Suit Your Requirement?
- The most appropriate Home Loan will rely on the property needs, and you have to check your financial profile and repayment ability, and then decide. The person who buys a ready-made residential property may have different needs than the one who is about to build on owned land, or someone who will have an existing residence renovated.
- Likewise, an existing borrower looking for either a balance transfer or a top-up may not have the same financial needs as that of a first-time Home Loan applicant. Loans Telangana assists consumers in understanding these options and finding the suitable products available from lenders registered with them, banks, and NBFCs.
- The lender determines final product availability, eligibility, and loan terms accordingly.
Who Can Explore a Home Loan?
- Different banks or NBFCs (non-banking financial companies) have their own criteria to assess the Home loan eligibility of each applicant.
- In terms of salaried applicants, income on a monthly basis plays a major role in credit scoring bodies, as well as (more or less) job stability, age profile, and number of EMIs currently being paid; employer type, etc are things that might be looked at before processing a loan application.
- Self-employed, professionals and business owners may be assessed based on business stability, annual income, financial statements, Income Tax Returns, banking activity, and other financial records.
- Age of the borrower, amount requested, property value, and loan term are also taken into consideration by the lender.
- Even if a customer meets all the minimum eligibility criteria, he or she can still go through elaborate credit, legal, and property verification before the lender finalizes.
- Secured loans with Loans Telangana can help salaried and qualifying self-employed clients identify which Home Loan solutions could meet their needs.
Home Loan Eligibility
Home Loan eligibility is a term associated with some basic criteria that the applicant presumably needs to meet against loan approval from a bank or NBFC. Requirements vary a tad from lender to loan product, to applicant profile.
Applicant Type
Salaried employees, eligible self-employed professionals, and business owners may explore Home Loan options. The required income documents and eligibility assessment can differ depending on the applicant’s employment or business profile.
Age
Applicants generally need to fall within the age limits specified by the respective lender. Age may also influence the maximum repayment tenure that can be offered.
Regular Source of Income
Applicants should generally have a regular and verifiable source of income. Salaried income, professional income, or business income may be considered depending on the applicant’s profile and lender requirements.
Employment or Business Continuity
Salaried applicants may need to provide evidence of steady employment, and self- employed individuals usually must demonstrate continuity of business or professional activity. This period varies from lender to lender.
Repayment Ability
The applicant should have sufficient income to manage the proposed Home Loan EMI along with regular expenses and existing financial commitments.
Credit History
Banks and NBFCs may review the applicant’s previous loan and credit repayment history as part of the eligibility assessment. Credit history is one of several factors considered and does not independently guarantee approval.
Eligible Property
The property being financed should meet the lender’s legal, technical, and valuation requirements. Property ownership, title, approved plans, and other relevant records may be reviewed.
Required Documentation
You do have KYC, Income /Banking/Property So Is Required Disclaimer: The document checklist varies according to the applicant profile, property type, and lender.
Factors That May Affect Your Home Loan Amount and Terms
After basic eligibility is established, several factors can influence how much Home Loan may be available, the repayment tenure, and the terms offered by the lender.
01
Income Level
The applicant’s monthly or annual income can influence the Home Loan amount that may be considered. Higher disposable income may support a higher eligible amount, subject to other lender conditions.
02
Existing EMIs and Financial Obligations
Existing loans, EMIs, and other financial commitments reduce the income available for a new Home Loan repayment. Higher existing obligations may therefore affect the eligible loan amount.
03
Credit Profile
Repayment history, outstanding credit, and previous defaults may influence the lender’s credit assessment. The impact can vary according to the lender’s internal policies.
04
Requested Loan Amount
The amount requested should generally be reasonable in relation to the applicant’s income, repayment capacity, and property value. A lender may sanction an amount different from the amount originally requested.
05
Property Value
The lender may take into account the appraiser’s value of the property when deciding on how much they are willing to lend. The borrower will make up the difference from the rest of his or her own funds.
06
Repayment Tenure
The selected tenure influences the EMI and total payout structure. The lender will offer you a tenure based on the available data to him, like age, income, and repayment capacity.
07
Property Location and Legal Status
The location, nature of property, legal title to land, necessary approvals, and technical state can affect acceptance by a lender. Some lenders even have specific area or property type serviceability requirements.
08
Co-Applicant Profile
If a co-applicant is included, the bank may evaluate the income, credit profile, and repayment capacity of a co-borrower based on its policies. In other cases, eligibility may be affected by combined income.
09
Internal Lender Policies
Every Bank & NBFC has its own slab for credit assessment, property policy, and risk criteria. This means that the same individual may be offered different loan amounts, a different tenure or term by various lenders.
Home Loan Interest Rate, EMI and Repayment Tenure
Home Loan interest rate, EMI, and repayment tenure are closely connected and together influence the monthly repayment amount and overall borrowing cost. The applicable structure depends on the lender, applicant profile, loan amount, tenure, and lending policies.
Home Loan Interest Rate
- The rate of interest on a home loan has a direct influence on both the EMI paid and overall repayments made over the loan tenure.
- The rate charged is also subject to the characteristics of the lender, applicant profile, credit assessment, loan amount opted for, along with tenure and prevailing lending policies.
- Loans Telangana guides customers to different options one can seek, but the final interest rate will be established only by the relevant bank or NBFC.
Home Loan EMI
- EMI stands for Equated Monthly Instalment; this is the amount which the borrower usually pays every month against the Home Loan.
- The principal, interest rate, and repayment tenure affect the EMI.
- While a longer tenure can help lower the monthly EMI, it will result in higher interest over the course of the loan. A shorter tenure can increase your monthly EMI, but can help in lowering the overall interest outgo.
- By the time you actually repay, the EMI should be within limits.
Home Loan Repayment Tenure
- This way, it is the most appropriate and crucial point to choose tenure, as that has a major impact on both the monthly EMI and the total cost of borrowing.
- Customers shouldn’t opt for a long tenure just because the EMI seems lower. Knowing the total interest to be paid over the entire duration gives a better understanding of the actual financial exposure.
- The maximum tenure is ultimately subject to the lender’s own set of eligibility rules.
Down Payment Requirement
- In most cases, the banks and NBFCs do not finance 100% of the property value.
- The borrower will most likely have to use a part of their own money as a down payment on the property.
- Customers will also have to set aside a separate budget for other property-related expenses, as some charges relating to the purchase are not covered in the property financing.
Home Loan Processing Fees and Other Charges
- In addition to interest, a home loan can also carry some other charges.
- Banks and NBFCs may levy processing fees for evaluating the application. There may also be a legal verification, technical valuation, or administrative fee depending on the transaction.
- The specific fees are lender- and product-dependent.
Documents Required for a Home Loan
The documentation is related to personal, income, and property for a home loan.
- Documents confirming identity and address, PAN, photographs, and perhaps banking details for KYC and applicant verification have to be provided by the applicant.
- Salaried customers may be required to show their salary slips, bank statements, Form 16, or other proof of income.
- For individual customers, this might include Income Tax Returns, business proof, financial statements (as applicable), and GST records & banking details in case of funding for financial purposes.
- Depending on the property and lender, property documents can include the sale deed, agreement of sale, title documents, records related to registration (in case the property is registered), approved plans, tax receipts, and any other legal or technical document.
- The final document checklist is provided by the respective bank or NBFC.
Home Loan Application Process
Understand Your Requirement
Identify the type of property, approximate property value, and Home Loan amount required.
Check Basic Eligibility
Your income, employment or business profile, age, existing obligations, and other details may be reviewed.
Prepare the Required Documents
Keep KYC, income, banking, and property-related documents ready for verification.
Explore Suitable Loan Options
Relevant Home Loan options available through participating banks and NBFCs may be considered.
Submit the Application
The selected financial institution receives the Home Loan application and required documents.
Credit and Property Verification
The lender may evaluate the applicant’s financial profile and conduct legal and technical verification of the property.
Loan Decision
The bank or NBFC determines whether the application is approved and decides the sanctioned amount and applicable terms.
Loan Disbursement
After approval and completion of applicable conditions, the lender processes disbursement according to its procedures.
How Loans Telangana Helps With Home Loans
Finding a Home Loan can become confusing when different banks and NBFCs follow different eligibility criteria, documentation processes, and lending terms.
- Loans Telangana helps simplify this process by first understanding the customer's requirements and basic profile.
- We can help customers understand the type of Home Loan they are considering, the general documentation required, and factors that lenders typically review.
- Relevant options available through participating banks and NBFCs may then be explored based on the information provided.
- The lender independently makes the final decision regarding approval, sanctioned amount, interest rate, tenure, and other applicable conditions.
Home Loan Assistance Across Telangana
Loans Telangana helps potential customers looking for home loan options in Hyderabad and other serviceable locations in Telangana.
The property requirements vary significantly based on the location, type of the property, price, and profile of the applicant.
If you want to purchase an apartment, independent house, or any other qualified residential home, understanding the financing structure provided by housing finance companies before proceeding with a purchase is likely to assist you in making a better choice.
On the other hand, lender serviceability can be different depending on property location as well as internal lending policies.
What Should You Check Before Choosing a Home Loan?
Do not just compare the interest rate on a home loan before availing one
Look at what the offered EMI is and if it is within your budget for a long duration. Find out the available tenure and total repayment commitment.
Investigate review processing and any legal, technical, administrative, or other lender fees.
Know the down payment and how much you will have to contribute personally.
Review prepayment and foreclosure clauses if you plan to pay the loan off ahead of time.
Lastly, do read the official sanction letter carefully before you accept the loan, as it has the real terms and conditions laid out by your lender.
Frequently Asked Questions About Home Loans
What is a Home Loan?
A Home Loan is a secured loan that may assist customers in purchasing or constructing residential property, subject to criteria based on eligibility. Terms as to eligibility, financing percentage, and other matters are set by the lender.
Is Loans Telangana a Home Loan lender?
No, Loans Telangana is neither a bank nor an NBFC nor a direct Home Loan Provider. We enable customers to explore Home Loan options suitable for them from the array of home loan options offered by participating banks and NBFCs.
Who can apply for a Home Loan?
- Salaried Employee – Home Loan eligibility for an individual with a steady monthly paycheck and stable employment may be checked.
- Self-Employed Applicants – Individual business owners, professionals for college admissions and indeed any other acceptable self-employed with income records, business validity and repayment capability may apply.
- Business Owners – Proprietors, partnerships and company owners could be viable candidates for Home Loan offers depending on the stability of their business, income and financial documents.
- Property Buyers – Holders intending to purchase eligible residential property, subject to property and lender requirements.
- Who are also known as the success or failure of lenders, sample lender criteria will be based on age, income, existing EMIs in the month, credit profile, CIBIL score, repayment capacity, occupation,y and bank/NBFC considerations.
How much Home Loan can I get?
It varies based on repayment capacity, income, property value, other existing liabilities, and the lender’s policy. After proper assessment, the bank or NBFC certifies the final approved amount.
What documents are required for a Home Loan?
Personal KYC, Income, Banking and property documents are things that the applicant generally needs to have with them. The exact document list is applicant profile-, property type-, and lender-specific.
Does a Home Loan require a down payment?
As lenders typically lend a percentage of the property value, there may be a requirement for the borrower to fund some of it from personal cash reserves, depending on specific requirements. This requirement varies depending on the lender’s policy.
Does Loans Telangana decide the interest rate?
No. The applicable Home Loan interest rate is determined by the respective bank or NBFC based on its lending policies and the applicant’s profile.
Can self-employed customers apply for a Home Loan?
Yes. Eligible business owners and self-employed professionals may explore Home Loan options. Lenders may review business income, financial statements, Income Tax Returns, bank statements, and other relevant records.
Does having a good credit profile guarantee Home Loan approval?
No. You are assessed in part based on past credit history. The bank can also determine the final decision based on income, repayment capacity, stable employment or business, verification of property-related documents, and internal lender policies.
How can I start my Home Loan enquiry with Loans Telangana?
Get in touch with Loans Telangana. You need to call us and give basic details about your property requirement, income/ employment profile, and the approximate loan requirement. We will then outline the next steps and potential options that are available.
Start Your Home Loan Journey With Loans Telangana
Buying a home deserves careful financial planning. Whether you are purchasing your first home, planning residential construction, or exploring an eligible property financing option, understanding the loan structure before proceeding can help you make a more informed decision.